Dmitry Mironchikov States There Is No Crisis in the Russian Dairy Industry
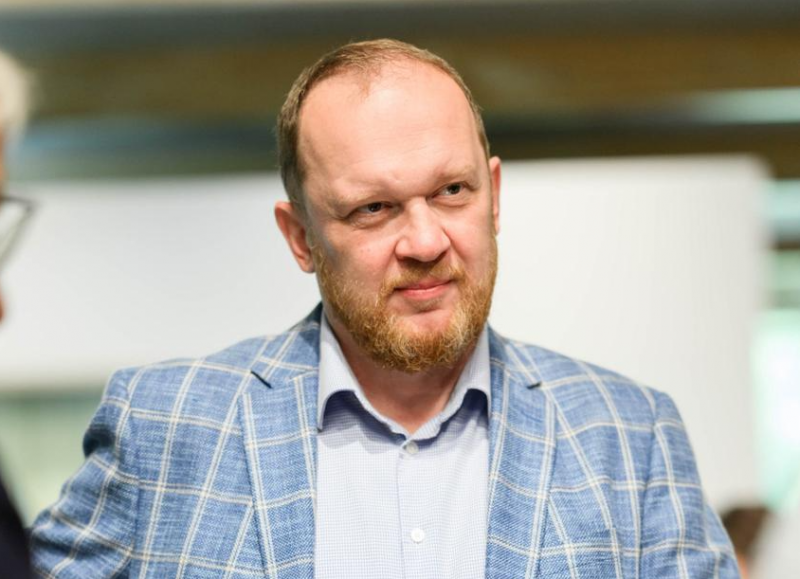
— Dmitry, we invite you to AqAltyn as an expert on the Russian market. We would like to see the real picture: what is happening with milk in Russia today?
— Without irony, the situation with milk in Russia is quite good. Consider what else can be done in agriculture right now. Grains and oilseeds are hard to export due to low prices, but the situation with milk, barring any epizootic issues, is generally positive.
If you calculate profitability per hectare, milk remains one of the most profitable agricultural businesses in most regions, alongside beef. Thus, interest in dairy farming continues.
— But is production still growing?
— The situation has changed here. At the beginning of the year, growth was at 4–6%, but in the last two to three months, it has essentially stopped. Year-on-year, there's still a slight increase, but that reflects the strong start to the year. By year's end, I expect only a minor increase.
The industry's consolidation continues, while production growth has halted. These are different processes.
— Why has it stopped?
— There are two main reasons. Firstly, Siberia and southern Russia have suffered greatly. Several regions faced serious epizootic issues, with some large farms losing many animals or culling entire herds. This significantly affected production.
Large companies can restore herds, but only with support. Here lies the second issue: government support has been significantly reduced due to budget constraints.
Currently, ongoing projects are mainly those started two or three years ago. New complexes for two to four thousand heads are being launched, and some farms are expanding capacity. However, few new projects are visible, so the growth seen in official statistics is largely the result of completing earlier investment cycles.
— So the term "dairy industry crisis" doesn't resonate with you?
— No crisis exists. There's negative dynamics. Development continues, albeit at a slower pace.
Milk is increasingly concentrated in large farms. Older and smaller farms are gradually disappearing. If someone closes a farm of 600–800 heads, they likely won't open a new one. A large holding will restore its herd and continue investing.
By my estimate, the top 50 producers now account for roughly 45–50% of Russia's market milk, and this share will increase. Small farms can't afford expensive specialists, and without a strong team, high productivity is unattainable. To balance the economy, you need high yields.
— You mentioned that milk is still profitable. What about the purchasing price?
— It has fallen significantly, by about 20–25% year-on-year. It slightly rose in September, leading to a paradoxical situation.
— Due to seasonality?
— Not only that. Mainly due to problems with palm oil. Following attacks on port terminals, supply disruptions arose, reducing available port capacity. The "palm" market shrank.
Our "supernatural product producers for the social sector" rushed to buy butter and cream. They don't purchase raw milk, as they lack the intake facilities. However, they actively pulled butter and cream from the market.
Consequently, milk fat substitutes became significantly more expensive. Two months ago, they cost about 120–130 rubles per kilogram; now it's around 220 rubles. Cream prices rose, pushing up raw milk prices.
Previously, I expected prices to remain stable through year's end: milk producers had decent economics, and processors did too. But the fat shortage shifted the balance. Prices vary greatly across categories.
— You mentioned palm oil issues. Are they related to the EFCO situation?
— EFCO indeed faced significant logistical challenges. After damage to Black Sea port terminals, Baltic port capacities were insufficient. Thus, the issue wasn't that the company stopped operations, but that importing goods became physically more challenging.
— But the company's leadership faced criminal prosecution. Did it affect operations?
— As far as I see, no. Besides the arrest of three leaders, management continues as usual. I noticed no changes in processes. The issue was port logistics.
This is crucial for the dairy market. When plant-based fat is scarce, substitute producers turn to dairy fat. Demand quickly shifts to cream and butter, although these businesses don't directly accept raw milk.
— Which category currently seems most problematic?
— Cheese. Butter stocks have declined over the past two months due to increased fat demand. Meanwhile, cheese stocks remain high — cheese sales have stagnated.
Whole dairy product companies are generally stable in processing volumes and economics. Margins allow operations. Cheese is more challenging: it's become very expensive for consumers.
— Kazakh processors complain that Russian and Belarusian butter arrives at prices they can't compete with.
— It depends on the specific price. Russia has always supplied dairy to Kazakhstan, as we both know. Currently, Russian and Belarusian butter prices are similar.
Belarusian enterprises indeed undercut prices in Central Asian markets. If we consider previous indicative prices, butter was sold to Russia at about 570 rubles per kilogram and to Central Asia at about $5.5, around 450 rubles. They needed to clear large stocks, including last year's butter.
Now, Belarusian stocks have noticeably decreased. They produce about 8–10 thousand tons monthly but sold 12–15 thousand, mainly to Russia and Central Asia. Therefore, I expect export indicative prices to rise.
— How do these Belarusian indicatives work? Are they strict limits?
— No, they're recommended parameters. However, if a price war begins, Russian regulators can quickly pressure suppliers.
In August, some enterprises tried experimenting — selling butter with less than 70% fat, as indicatives were set for 70% and above, and 80% and above categories. The response was almost immediate.
Last year, Belarusians under-delivered, while this year, they over-delivered dairy to the Russian market. Thus, balances aren't absolute — regulators react stringently mainly when pricing corridors are breached.
— But why is Kazakh butter more expensive despite local milk?
— Consider raw material prices. In Kazakhstan, raw milk costs similar to Russia, and in some regions, even more. We recalculated during our conversation: in East Kazakhstan, it's about 285 tenge per kilogram, including VAT, roughly 53 rubles. In Almaty region — about 305 tenge with VAT, around 57 rubles at the time. In Siberia, similar milk costs about 46–47 rubles.
The tenge closely links with the ruble. When the ruble weakens, Russian products become more competitive, boosting exports. Currently, Russian skimmed milk powder is among the cheapest from major producing countries, prompting widespread exports.
Kazakhstan shares a customs space with Russia and Belarus. Local processors don't always favor this. Yet, if imports are restricted, one must consider: what will happen to shelf prices, and can consumers afford products?
— So market protection alone won't solve the issue?
— It won't. Cost management is needed. Kazakhstan requires its own milk, but increasing cow numbers alone isn't enough. Without production culture, fodder base, veterinary health, and specialists, no miracle will occur.
In Kazakhstan, agricultural organization production is indeed growing. The south, around Shymkent and Turkestan, where AqAltyn will be held, is particularly interesting. There's a real boom: new farms are being built, animals imported, investments are flowing. This seems to be Kazakhstan's fourth attempt to systematically increase milk production.
The main question is what will come of it this time. If milk production surges, it needs a market. Thus, processing and market development must accompany farm growth.
— What is happening with demand in Russia? In 2023–2024, it was driven by "military money." Has this wave ended?
— Yes, in 2025, demand fell by about 4–5% in physical terms. I focus on kilograms, not rubles, as financial indicators rise with prices.
The steepest decline was in butter and cheese — the most expensive categories. Raw materials initially rose by about a quarter, finished products followed, and when raw prices fell, retail prices didn't drop quickly. Consumers reacted to this.
Recovery is underway. Butter sales are growing, although not back to previous levels. Whole dairy products suffered less and are already showing growth. People gradually adapt to new prices. If no sudden price jumps occur, consumption may increase by about 1–2% annually.
— Who captures this growth — Russian companies?
— Largely Belarusians. Belarus adds about 300–400 thousand tons of milk annually. Productivity increases, farms are built, and animal imports are allowed again. The domestic market is small: the population is around nine million and declining, with stagnant consumption. Thus, surplus milk primarily goes to Russia.
The Russian market remains Belarus's main and most profitable one. If Russia's overall demand grows by a few percent, Belarusian enterprises can capture a significant portion of this growth.
— You mentioned that major processors feel stable. For instance, what's happening with PepsiCo's former dairy business?
— It's doing well: volumes are shrinking, but profitability is rising. The company reduced its range, optimized production sites and costs. Last year, it sold its Ufa site, focusing production in other regions. Financially, they're doing fine.
This exemplifies how large businesses become more efficient. Fewer sites, fewer product lines, lower costs — yet stable economics.
— Returning to cheese. How deeply have prices fallen there?
— Russian producers are already lowering prices. Standard semi-hard "Dutch" cheese reached about 430 rubles per kilogram. Converted back to milk, this is not very convincing economically for producers.
The market for cheap cheese products is also shrinking. Tax authorities audit producers, demanding VAT surcharges. Traceability systems are tightening: if you didn't buy vegetable fat, it can't just appear in the finished product. For large companies, working through shell companies is too risky.
There were periods when control was eased to keep butter shelf prices stable. Then, many dubious products appeared in stores. After price stabilization, such suppliers were removed again. Now, there's less room for blatant falsification.
— So during the butter crisis, substitutes were deliberately allowed on shelves?
— I'd say about two years ago, when wholesale butter prices neared a thousand rubles per kilogram, regulators subtly indicated not to clamp down too hard on the market. The goal was to keep shelf prices stable.
Many producers, rarely seen in major chains before, entered the market and occupied shelf space over a year. Once the situation with real butter stabilized, control increased again — now, most such brands aren't found in federal chains.
— So the market created a window for them and then closed it?
— Precisely. They were allowed as a temporary price buffer, and when the need disappeared, they were systematically removed.
— One noticeable consumer trend is high-protein products. Has it reached Russia yet?
— Yes, certainly. Companies produce high-protein dairy products and many are exploring this space.
However, this market's capacity is still small. A trend emerges, there's much discussion, then the product finds its niche. Consider plant-based drinks: there was a boom and predictions that they'd capture nearly half the market by 2030. The category found its buyer, but there's no explosive growth anymore.
I believe high-protein products will follow a similar path. They'll remain part of healthy nutrition but won't displace traditional dairy products.
— And cottage cheese? We notice growing interest even in countries where there was little such culture before. We joked that many people from Russian-speaking countries have moved abroad in recent years, creating demand for cottage cheese in new places like Vietnam, Indonesia, and other countries.
— That's indeed the case. People move, but their dietary habits remain. Living without cottage cheese is tough, laughs Dmitry Mironchikov. As a result, local producers begin to meet this demand.
— Speaking of exports to distant countries: Russia's exports were small. Has anything changed?
— Why small? In 2023–2024, Russian companies actively entered the Algerian market with dry milk, with good volumes going to the Middle East. Last year, the ruble exchange rate held back exports. At approximately 85–90 rubles per dollar, shipments become economically viable again, and major players are returning to foreign markets.
— Yes, but looking at overall imports by China, Saudi Arabia, or the UAE, Russia's share is still very small.
— But we have a clear competitive advantage — cheap dairy proteins: skimmed milk powder, whey, and other ingredients. There's also ice cream exports — a separate stable market.
If Russia exports 10–15 thousand tons of SMP to Algeria annually, I wouldn't call it insignificant. Plus, large shipments go to Kazakhstan and Uzbekistan. In certain months, domestic SMP prices rise precisely because significant volumes were exported, including to Algeria.
— But can current logistics halt this export?
— Logistics is indeed a serious challenge. Black Sea port capacities are limited, and railways are overloaded. Companies use the Baltic, Far East, and seek alternative routes.
However, trade doesn't stop. People adapt and find solutions. Thus, I don't think exports will disappear. The future dynamics depend heavily on external factors and the ruble's exchange rate.
— But Russia itself relies on dairy fat imports. What happens when usual supply channels close?
— Alternative routes are always found. When a deficit arose, Indian butter entered the market, helping stabilize the situation. Around 20 thousand tons were imported. Supplies from Iran resumed.
It's debatable where this butter is produced and from what raw materials, as statistics are unclear. I estimate Russia consumes about 300 thousand tons of butter, with roughly 100 thousand from Belarus and about 300 thousand produced domestically. Clearly, the numbers don't align.
Some products may be made from milk fat substitutes, others repackaged. Kazakhstan shows a similar pattern: raw milk is scarce, yet official butter production grows. Thus, one should cautiously interpret record figures and consider raw material origins.
The main takeaway is simple: even with terminal damage and restricted routes, trade continues. India, Iran, and alternative logistics routes — the market seeks replacements.
— Let's discuss fuel. How has its price increase impacted the dairy industry?
— In certain regions, the problem was acute. Supply disruptions occurred in summer, and logistics became costlier. However, considering milk processing, we estimated fuel and tariff cost impacts at a maximum of about 2% of the product's final price.
Thus, fuel issues alone won't collapse the industry. The problem lies in rhythm disruptions. Raw milk can't be stored long: it must be collected daily from farms and processed. Therefore, any logistics failure is more sensitive for dairy producers than many other sectors.
— How do you see the Russian market in the coming years?
— I believe it will be fairly stable. There won't be explosive growth, but I don't expect a systemic decline either. Consumption will gradually recover, with milk production potentially growing by 1–2% annually.
Much depends on how and when the current geopolitical situation resolves, the exchange rate, and export route availability. A more precise forecast now is akin to reading tea leaves.
The previous productivity growth resource is gradually depleting. If a modern farm produces less than 11 thousand kilograms per cow annually, it's already deemed inefficient. At such levels, each subsequent step is more challenging.
— The government aimed to add several million tons of milk. How realistic is this?
— Technically, increasing production is possible. However, I always question: why? If the goal is to add six million tons, it's crucial to understand who will buy this milk.
Relying solely on China is no longer possible: China rapidly increases its production and begins exporting certain dairy products, including butter. Therefore, growth should be based on specific markets and clear demand. Merely producing additional volumes to meet targets isn't a strategy.
— Is vertical integration a prerequisite for efficiency? Must a farm process all its own milk?
— Not necessarily. Sometimes the owner says, "We process all our milk," and I ask: why? Selling your milk can be profitable, and for processing, you can purchase cheaper raw materials on the market.
Vertical integration works when the holding's internal economics are well-structured. Merely having both a farm and a plant doesn't guarantee profitability.
— Yet agriculture remains a resilient business?
— It remains as resilient as ever, especially milk. In European Russia, excluding some southern regions, it's one of the most profitable ways to utilize land through livestock.
Don't expect explosive growth, but the sense of industry collapse isn't present either. People continue with dairy because, under current conditions, it's one of the few understandable and predictable agricultural businesses.
— What do you expect from AqAltyn?
— This is a new event for me. The last major forum in the region I attended was the Dairy Olympics in Tashkent. Interesting people always gathered there. AqAltyn, as I understand, will have a more targeted audience.
I'm primarily interested in observing and listening. I've had projects in Kazakhstan and currently have projects in Uzbekistan. I want to understand how adequately market participants assess their dairy industries, what they see as primary constraints, and where they plan to go.
Of course, the staffing topic is crucial. You can invest in a farm, buy animals and equipment, but without specialists, nothing works. Our countries remain friendly, so there's a need for competence and personnel exchange. Already, many Russian and Belarusian specialists work in Kazakhstan and Uzbekistan. I think this process will continue.
Dmitry Mironchikov is an independent dairy industry consultant and one of the most experienced Russian specialists in the raw milk market. He has spent a significant part of his professional career within a large dairy company, serving as PepsiCo Russia's raw milk procurement director. In this role, Mironchikov was responsible for a key production chain link — supplying processing plants with raw materials — and worked directly with agricultural producers from various regions of the country.
The General Partner of AqAltyn - Borte Engineeringhttps://engborte.kz/
Borte Engineering, a leading national producer in Kazakhstan, creates high-tech equipment for the food industry, confirmed by its inclusion in the Register of Domestic Producers. The company successfully collaborates with enterprises throughout Central Asia, strengthening the regional economy.
Event partners also include:
The Dairy Union of Kazakhstanhttps://kazsut.com/
France Grouphttps://francegroup.org/ru