Synlait reported a $75.4m full-year loss
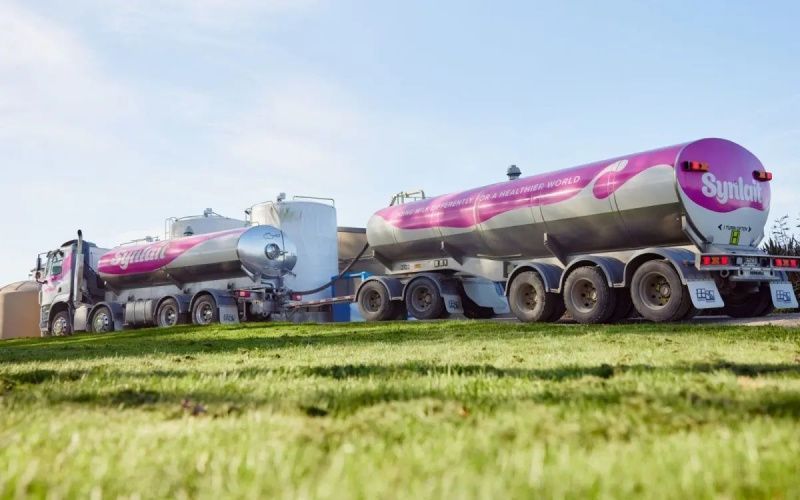
Synlait reported a full-year loss of $75.4m. Manufacturing stabilisation during the second six months was accompanied by a net profit of $5.2m and reported earnings before interest, taxes, depreciation and amortisation (EBITDA) of $42.8m for that period.
Factory reliability improved during the year. The company’s Manufactured in Spec measure rose from 91% in the first half to 95% in the second half, and reached 99% by August. Underlying full-year EBITDA was $46.3m, compared with reported EBITDA of $8.1m.
Synlait’s balance sheet remained under pressure. Net debt stood at $215m at year-end, while debt-service obligations and leverage were identified as material going-concern risks.
Supplier retention was described as an urgent strategic priority as Synlait works to defend its Canterbury milk pool against competing procurement efforts. Management confirmed a final base milk price of $9.69 per kilogram of milksolids for the 2025/26 campaign. Average incentive premiums of $0.38 brought the aggregate payout to $10.07 per kilogram of milksolids, the second-highest level in the company’s history.
For the 2026/27 season, Synlait set opening advance guidance at a base price of $9.50 per kilogram of milksolids. The company said the level was intended to deter supplier departures as dairy farmers consider alternative off-take agreements.
Synlait has completed the sale of its Pokeno manufacturing facility in the North Island. The transaction raised capital for reducing net debt. Management’s recovery plan consists of three stages—stabilise, simplify and scale.
Under the planned operating model, Synlait will concentrate on manufacturing returns and capacity utilisation across its core Canterbury processing assets. The company will also draw on the backing of Bright Dairy, its majority Chinese shareholder.